In every state, app-based payday loans carry triple-digit annual percentage rates or APRs, and borrowers paid one or more fees, including fees disguised as “tips,” on a majority of payday loan app transactions, according to a report by Julian Bond Institute, part of the Center for Responsible Lending, or CRL.
These payday loan apps trap borrowers in a cycle of debt, extracting the bulk of fees from borrowers with 25 or more loans a year.
“Our state-by-state data show that payday loan apps charge triple-digit interest rates and rely on people taking out dozens of loans a year to generate most of their fees,” Christelle Bamona, co-author of the analysis and senior researcher at CRL, an advocacy group, said in a statement. “This business model should concern policymakers.”
Bamona said strong interest rate caps need be applied to these predatory loans to protect consumers.
CRL’s analysis was based on a dataset showing bank account transactions for nearly 347,000 borrowers of payday loan apps.
Based on a nationwide sample of these borrowers, CRL found the following about direct-to-consumer payday loan apps:
- The APR of the average loan is 232 percent.
- 96 percent of loans had fees, including fees disguised as “tips.”
- 82 percent of fees were extracted from people with 25-plus loans a year.
The analysis also found the following about all payday loan app advances, those from employer-based and from direct-to-consumer lenders:
- 42 percent of loans were smaller than $100.
- On average, borrowers took out 33 loans a year.
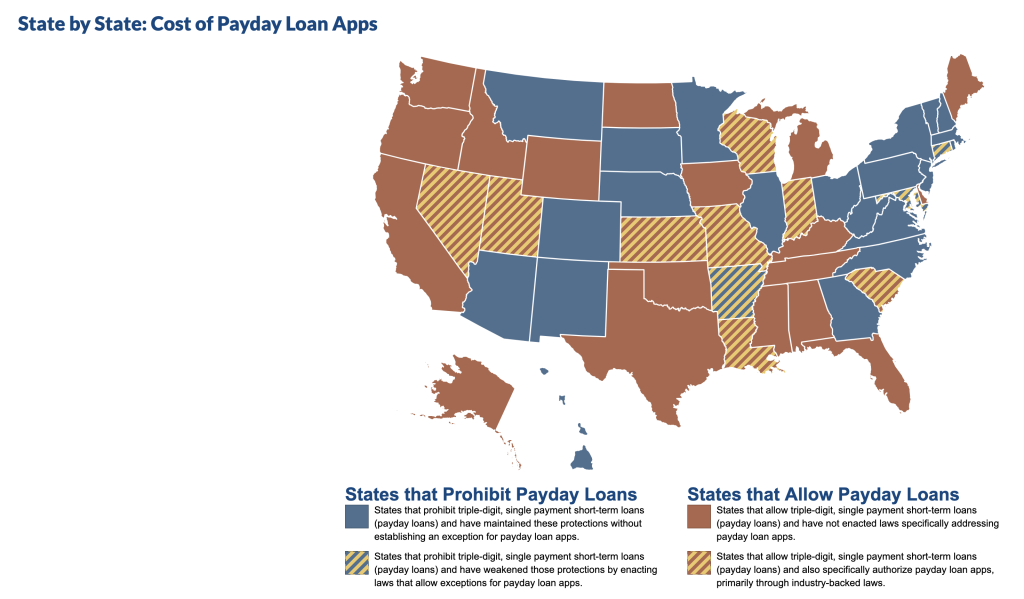
An interactive map displaying the research categorizes state law for payday loans. App-based payday lenders have been charging triple-digit interest rates even in states that prohibit lending at those rates.
Some state and local governments have sued companies for violating their usury laws as documented in CRL’s Litigation Tracker. As shown in the map, some states have exempted payday loan apps from consumer protection laws.
The U.S. House of Representatives Committee on Financial Services has voted to send to the full House a bill that would exempt these companies from state and federal laws that prohibit usury, discrimination, hiding costs, and overcharging military servicemembers.